


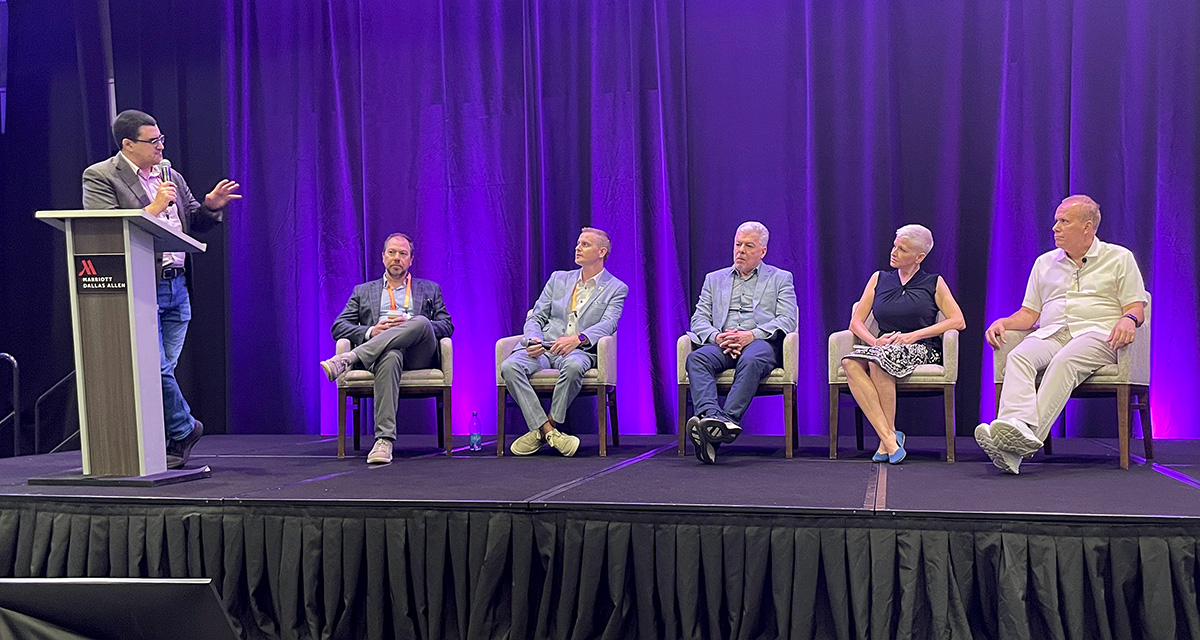
For years, movie theatre operators have been told they need to sell the experience, not just the movie. At CinéShow 2026 in Dallas, Texas, that advice took on a considerably more granular meaning: exhibitors are increasingly having to sell the individual auditorium.
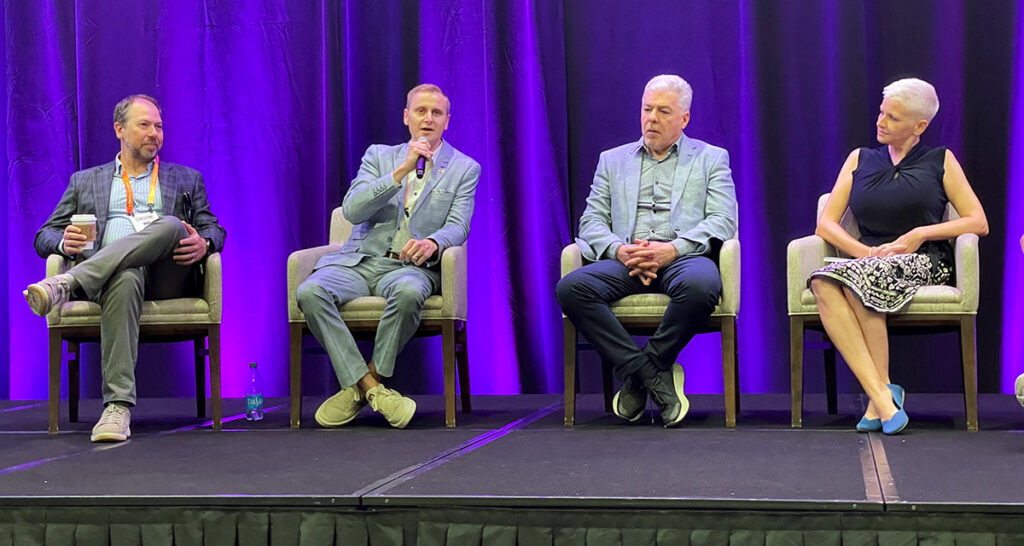
That was one of the more interesting takeaways from one of the events panel discussions, “Exhibitors & Tech Partners Fueling Box-Office Growth.” Inevitably, much of the conversation turned to premium formats, as cinema industry panels tend to do these days. But the discussion moved beyond the familiar argument that audiences will pay more for experiences they can’t replicate at home.
The more complicated question is what happens once a multiplex contains several of those experiences.
A Portfolio, Not a Single Format
B&B Theatres, for instance, has built a strategy around offering moviegoers a range of formats and concepts rather than relying on one premium auditorium. Depending on the location, that can include the circuit’s proprietary Grand Screen, ScreenX, 4DX, MX4D, D-BOX, screenPLAY! and other concepts ranging from Max Relax seating to Lyric and Marquee Suites. “We love concepts. We love to give customers a lot of options,” said B&B Theatres’ Brock Bagby.
At a 12-screen location, Bagby said, perhaps half the auditoriums might contain some kind of differentiated concept while the remainder retain a more traditional recliner configuration. The idea is not to premiumize every room, but to give audiences a choice in how much they want to spend and how they want to experience a particular film.
“What we continue to find on movies such as ‘Spider-Man’ is people have their format they want, and they’re seeking it out,” Bagby said.
Premiumization is no longer necessarily about steering a moviegoer toward the biggest screen in the building. Increasingly, exhibitors are offering multiple versions of “premium,” each with its own technology, price point and value proposition.
Which creates another problem: moviegoers have to understand what all of them are.
Daniel Loria, editorial director of Boxoffice Pro and moderator of the CinéShow panel, summed up the evolution neatly. “We’ve gone from marketing a movie to marketing a theatre, and now we’re marketing auditoriums,” he said.
That may be one of the less discussed consequences of exhibition’s continuing investment in premium formats. A consumer may already understand what IMAX means. Explaining the difference between a circuit’s proprietary large format, motion seating, 4D, enhanced audio, an upgraded seating concept or some combination of those technologies requires more work.
The Branding Problem
Regal Chief Commercial Officer Adam Rymer acknowledged that branded offerings can be particularly challenging. “We all suffer a little bit from some of our proprietary formats, whether that’s XD or RPX or SuperScreen or whatever it might be, and having the consumers understand what that is,” he said.
For exhibitors, that means the marketing job doesn’t necessarily end when a studio convinces somebody to see a movie. The theatre still has to explain why the customer should see it in one auditorium rather than another, and why the experience merits an additional charge.
Bagby said B&B has increasingly tried to do that directly, including through a social video series in which he explains the technology behind various theatre concepts. “A lot of them don’t get it,” he said of consumers. “They know it’s a big-ass screen, right? But they don’t get anything else.”
Explain the sound system, screen or projection technology, however, and Bagby said audiences — including a new generation of technically curious cinephiles — become considerably more interested.
The challenge becomes even more complicated when studio marketing enters the equation. Rymer said Regal works with distributors to understand which premium formats they intend to support and to obtain marketing assets appropriate for individual locations. Sometimes, however, those efforts collide with format-specific studio campaigns.
Regal has received one-sheets promoting a film in IMAX for theatres where the circuit does not operate an IMAX auditorium. Putting that poster in the lobby can amount to advertising another theatre in the same market. “We’re basically promoting our competition,” Rymer said. “This is something we need to push back on.”
It is a small example of a much larger change in theatrical marketing. As premium formats proliferate, a studio campaign built around one branded experience may help sell the movie while simultaneously steering customers toward whichever exhibitor in a given market happens to offer that format.
Disney is already trying to address a version of this problem with Infinity Vision, the premium-auditorium certification and marketing program it unveiled at CinemaCon earlier this year. Disney’s head of global theatrical distribution, Andrew Cripps, said during an ICTA event in Barcelona in June that there were roughly 75 exhibitor-owned premium large format brands in North America and more than 320 worldwide. “It’s very difficult — impossible — for us to effectively market all of those brands,” Cripps said. Infinity Vision is intended, in part, to give Disney a common marketing label it can use to steer moviegoers toward qualifying premium auditoriums that might otherwise carry dozens of different exhibitor-owned names.
That doesn’t eliminate the branding problem. If anything, the need for a program like Infinity Vision illustrates how complicated the premium marketplace has become. A cinema may have invested substantially in an excellent proprietary large-format auditorium, but unless audiences understand what the name means, the exhibitor still has to persuade them that the experience is worth seeking out… and paying more for.
What the Market Will Bear
There is also no universal formula for deciding which premium experiences make sense.
Cinemark International President Valmir Fernandes said the premium-format conversation in Latin America has evolved much as it has in the United States, with exhibitors offering customers more choice, but price sensitivity makes the economics considerably different.
“The formulas that work for some premium formats here, cost-wise, don’t work necessarily in Latin America,” Fernandes said. That doesn’t mean audiences in the region won’t pay for premium experiences. Fernandes said they will, when the location and product are right. The challenge is being more selective about where to make the investment and how much of an upcharge a particular market can sustain.
Fernandes said one of the more reliable ways Cinemark has found to build that audience is through its loyalty program, steering its most frequent moviegoers toward premium formats first. “They value cinema more than the non-frequent user,” he said, and those members tend to be more receptive to trying a premium auditorium once they’re offered the chance. He described it as a lower-risk way to accelerate the shift from standard to premium screens, market by market, rather than relying on price cuts or broad marketing to do the job.
The same calculation applies within the United States. Bagby said B&B has learned to set lower base ticket prices in smaller markets, allowing it to add a premium-format surcharge without pushing the total ticket price beyond what the local market will bear.
“That’s something we actually had to learn the hard way in a couple markets,” he said.
The lesson is particularly relevant for independent and regional exhibitors looking at premium-format investments. Adding a premium auditorium is only one part of the equation. An operator also has to determine what the local audience will pay for it, how often suitable films will be available and how the format fits with the other auditoriums at the complex.
The Scheduling Problem
Pricing is only part of the calculation. The next challenge is keeping a premium room productive. As operators add more premium rooms, those screens become valuable assets that have to be kept productive. Rymer said Regal spends significant time analyzing when audiences are coming, which customers are likely to respond to a particular format and how different films might be scheduled across those screens. “You now have an asset inside of your theatres which needs to be monetized,” he said.
That becomes especially tricky when multiple films capable of supporting premium pricing arrive at roughly the same time.
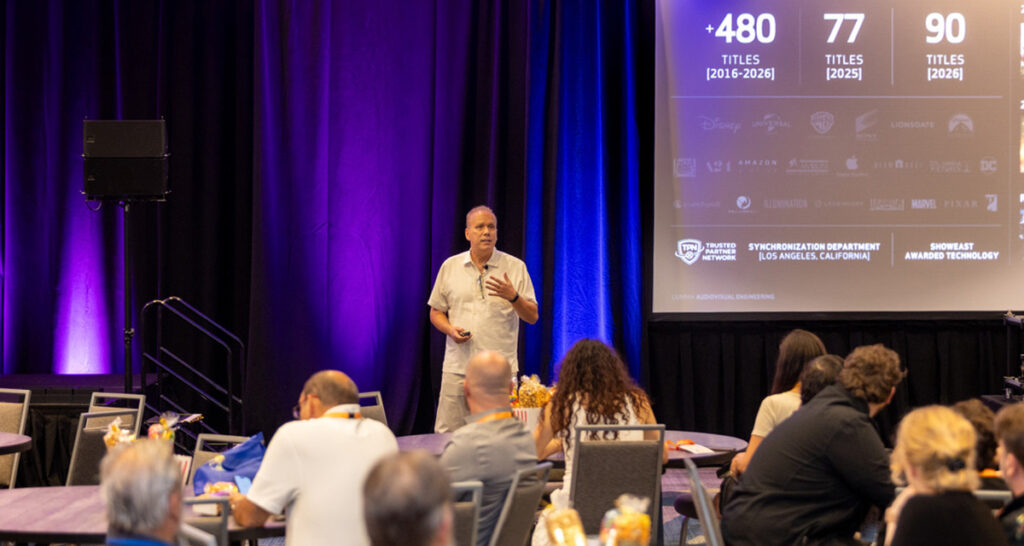
It is one reason Lumma partner and board member Rolando Rodriguez argued that the next stage of premiumization may involve not simply adding a premium format, but adding enough differentiated experiences that an operator is not forced to choose between titles.
Rodriguez, whose company offers 4D E-Motion and the lower-cost Magnify 8 format, cited investments ranging from roughly $60,000 to $70,000 for Magnify 8 up through substantially more expensive large-format installations, with motion-seating auditoriums falling somewhere between.
The precise economics of any installation will naturally vary by theatre, market, utilization and deal structure. But the larger point echoed what exhibitors on the panel were saying: premium has become less a single category than a portfolio.
Nicole Woods, RealD’s vice president of cinema and content partnerships for the Americas, framed that same portfolio logic from the opposite direction: for exhibitors with 3D-capable auditoriums already in place, differentiated premium inventory may already be sitting in the building. RealD is encouraging operators to treat 3D as a year-round strategy — spanning animation, concert films, anime, horror and repertory releases — rather than as an occasional offering tied primarily to tentpoles.
Whether every one of those formats ultimately earns a meaningful premium from audiences will depend on the market. The important shift is that exhibitors are increasingly thinking about their auditoriums in much the same way they think about their film slate: as a collection of different products aimed at different customers.
That makes the multiplex of the future considerably more complicated to operate… and arguably more resilient, provided audiences can find their way to the right room.
Right now, exhibitors are largely solving that problem individually rather than collectively. Bagby’s answer has been to go directly to consumers himself, on camera, explaining what a laser projector actually does. Rymer’s answer has been to push back on studios for sending the wrong marketing assets to the wrong theatres. Both are reasonable responses to the same underlying gap: the industry has not yet developed a shared consumer vocabulary for premium formats comparable to the one IMAX built for itself over decades. Infinity Vision is one attempt at a shortcut. It won’t be the last.
For an industry that spent decades largely marketing what was playing, the next competitive battleground is explaining, room by room, why it’s worth paying more to watch it there instead.
- Cinemas Aren’t Just Marketing Movies Anymore. They’re Marketing Auditoriums - September 15, 2026
- The Cinema Concession Stand Is Becoming a Marketplace - September 11, 2026
- Cinergy and Cinema United’s Todd Halstead Honored at CinéShow as Flix Brewhouse’s Allan Reagan Puts Ukraine Center Stage - August 31, 2026